Wind mitigation inspection
Inspection · Cloudbreak team · Updated October 29, 2026 · 9 sources
Definition
A wind mitigation inspection is an inspection that documents how well a building's construction resists wind: the roof covering, how the roof deck and roof are attached, the roof shape, secondary water barriers and protection of windows and doors. Insurers use the signed report to apply windstorm premium discounts or credits. In Florida, the inspection is recorded on the state's Uniform Mitigation Verification Inspection Form, OIR-B1-1802, which insurers must accept for the wind discounts Florida law requires.1,2,3
How it works
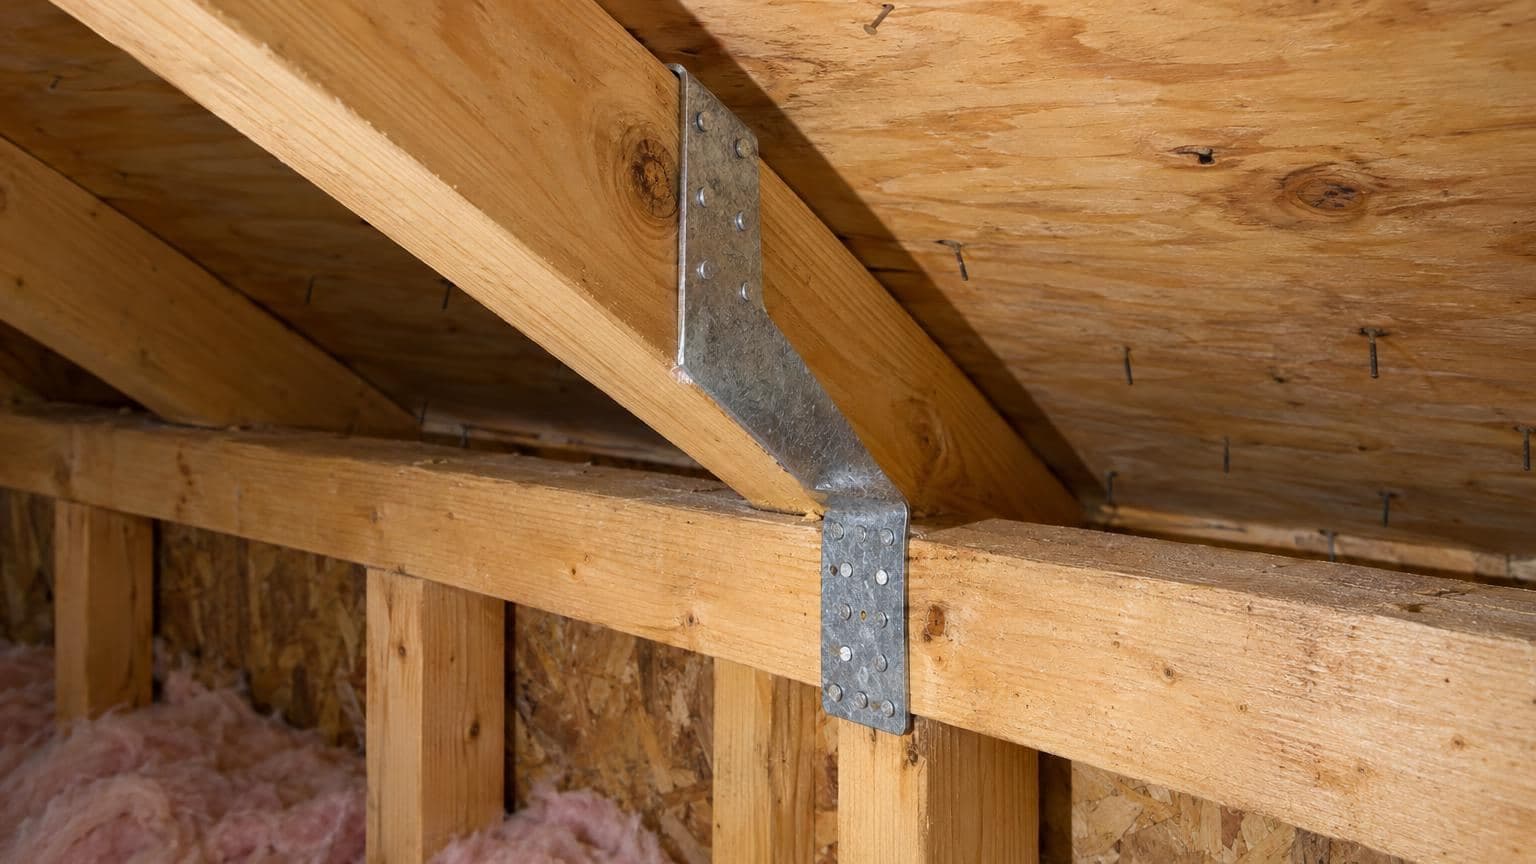
Wind damage usually starts at a building's weak points: the roof covering, the attachment of the roof deck, the connection between roof and walls, and windows and doors that let wind inside. A wind mitigation inspection checks each of these and records what was found.
The inspector visits the building, looks at the roof and, where possible, the attic, and photographs or documents each feature. The insurer then rates the building's wind exposure on what the report shows. Features that are not documented, such as roof-to-wall connections hidden in an attic the inspector cannot reach, may earn no credit.
Credits apply to the part of the premium that covers wind, so the inspection changes that portion, not the whole premium.
Florida: the uniform form
Section 627.0629, Florida Statutes, requires residential property rate filings to include actuarially reasonable discounts, credits or deductible reductions for construction shown to reduce windstorm loss, including roof strength, roof covering performance, roof-to-wall strength and opening protection. Section 627.711 has the state adopt one uniform inspection form that all insurers must use when a policyholder submits it for wind discounts.2,3
The current form, OIR-B1-1802 (Rev. 04/26), asks nine questions: the building code in force at permit application, the wind region by ASCE 7-22 design wind speed (Region 1 is 140 mph or more, Region 2 is 130 to 139 mph, Region 3 is under 130 mph, plus the High-Velocity Hurricane Zone), roof slope, roof covering, roof deck attachment, roof-to-wall attachment, roof shape, secondary water resistance and opening protection. For deck attachment, roof-to-wall connection and opening protection, the inspector records the weakest type found.1
At least one photo or document must back each feature marked in questions 2 to 9. A FORTIFIED Home Roof, Silver or Gold certificate can validate several of them. Citizens says a home whose attic the inspector cannot reach may not be eligible for roof-to-wall, roof deck or secondary water resistance discounts.1,4
Insurers must accept a form signed by a licensed home inspector with at least 3 hours of approved hurricane mitigation training and a passed proficiency exam, a certified building code inspector, a licensed general, building or residential contractor, a professional engineer or an architect. The signer must inspect in person, though engineers and contractors may send a direct employee. The insurer may have any form independently verified at its own expense.2
A completed form is valid for up to 5 years if no material changes are made to the structure and no inaccuracies are found. Inspections on or after April 1, 2026 must use the Rev. 04/26 form; earlier inspections may use Rev. 01/12. Knowingly submitting a false form to get a discount is a first-degree misdemeanor.5,2
Example
The state's notice to homeowners, OIR-B1-1655, says discounts apply only to the hurricane-wind portion of the premium, and that homes built under the 2001 Florida Building Code or later (or the 1994 South Florida Building Code in Miami-Dade and Broward) are eligible for a minimum 68% discount on that portion. Applied to an example home policy:6,7
| Before discount | After discount | |
|---|---|---|
| Hurricane-wind premium | $8,000 | $2,560 ($8,000 minus 68%, or $5,440) |
| All other perils premium | $4,000 | $4,000 (unchanged) |
| Total annual premium | $12,000 | $6,560 |
Discounts do not add together. The homeowner notice says the total is not the sum of the individual discounts: when one is applied, the others shrink until the policy reaches the insurer's maximum.7
Where you'll see it in Florida
- Policy notices: insurers must send OIR-B1-1655, the Notice of Premium Discounts for Hurricane Loss Mitigation, with each new personal lines residential policy and at each renewal.2,6
- Discount tables: forms OIR-B1-1699 (single family) and OIR-B1-1700 (non-single family residences) show the ranges of wind premium credits for existing construction under Rule 69O-170.017.6
- Apartments and condos at Citizens: OIR-B1-1802 covers 1 to 4 unit dwellings and residential buildings of 1 to 3 stories, including apartments and condos of 5 or more units. Commercial residential buildings of 4 or more stories use Citizens' MIT-BT II and III form, and commercial nonresidential buildings use form WPD-1C for opening protection.4
- Flat roofs: question 7, roof geometry, classes a roof on a building with 5 or more units as flat when at least 90% of the main roof area has a roof slope of less than 2:12.1
- Roof condition: Citizens' guide for the Rev. 04/26 form says it verifies only wind mitigation features and is not proof of roof condition or replacement.8
Questions
- How long is a wind mitigation inspection good for in Florida?
- Up to 5 years, as long as no material changes are made to the structure and no inaccuracies are found on the form.5,6
- Who can do a wind mitigation inspection in Florida?
- Section 627.711 lists licensed home inspectors with hurricane mitigation training, certified building code inspectors, licensed general, building or residential contractors, professional engineers and architects. An insurer may also accept others it considers qualified.2
- Does a wind mitigation inspection lower the whole premium?
- No. Credits apply to the part of the premium that covers wind. In Florida, the state's notice to homeowners says the discounts apply only to the portion of the premium that covers wind, whether or not a hurricane occurs, and that they are not cumulative.7
- Is Florida's new 2026 form required if I have an older one?
- Inspections on or after April 1, 2026 must use the Rev. 04/26 form. Citizens says it will keep accepting a Rev. 01/12 form completed within the 5 years before that date if the structure has not changed, and that the new form does not change the credits it applies for now.5,9

Cloudbreak
Cloudbreak's certified inspection partners record every roof section, elevation and exterior item before a loss, with an exception list for anything not captured. Before a purchase, the due diligence inspection covers storm risk, roof life and insurance cost.
Sources
Written by the Cloudbreak team. Numbers, dates and rules cite the published sources below.
- 1. Florida Office of Insurance Regulation: Uniform Mitigation Verification Inspection Form, OIR-B1-1802 (Rev. 04/26)
- 2. The Florida Legislature: Section 627.711, Florida Statutes: Notice of premium discounts for hurricane loss mitigation; uniform mitigation verification inspection form
- 3. The Florida Legislature: Section 627.0629, Florida Statutes (2025): Residential property insurance; rate filings
- 4. Citizens Property Insurance Corporation: Your Wind Mitigation Inspection
- 5. Florida Department of Financial Services: Mitigation Notices, Inspections and Forms
- 6. Florida Office of Insurance Regulation: Wind Mitigation Resources
- 7. Florida Office of Insurance Regulation: Notice of Premium Discounts for Hurricane Loss Mitigation, OIR-B1-1655
- 8. Citizens Property Insurance Corporation: Wind Loss Mitigation Guide for use with the OIR-B1-1802 (Rev. 04/26)
- 9. Citizens Property Insurance Corporation: Uniform Mitigation Verification Inspection Form Changes (March 19, 2026)