IBHS FORTIFIED
Risk · Cloudbreak team · Updated October 29, 2026 · 19 sources
Definition
IBHS FORTIFIED is a voluntary construction and re-roofing program from the Insurance Institute for Business & Home Safety (IBHS) that strengthens homes and commercial buildings against severe weather such as high winds, hail, hurricanes and even tornadoes. Its three levels, Roof, Silver and Gold, each include the level below.1
How it works
FORTIFIED goes beyond building code. An owner builds or re-roofs to the standard, an evaluator checks the work, and the building receives a designation, or for some commercial buildings a letter of compliance, for the level met. Owners use it to show insurers the upgrades and to qualify for discounts and grants where they are offered.
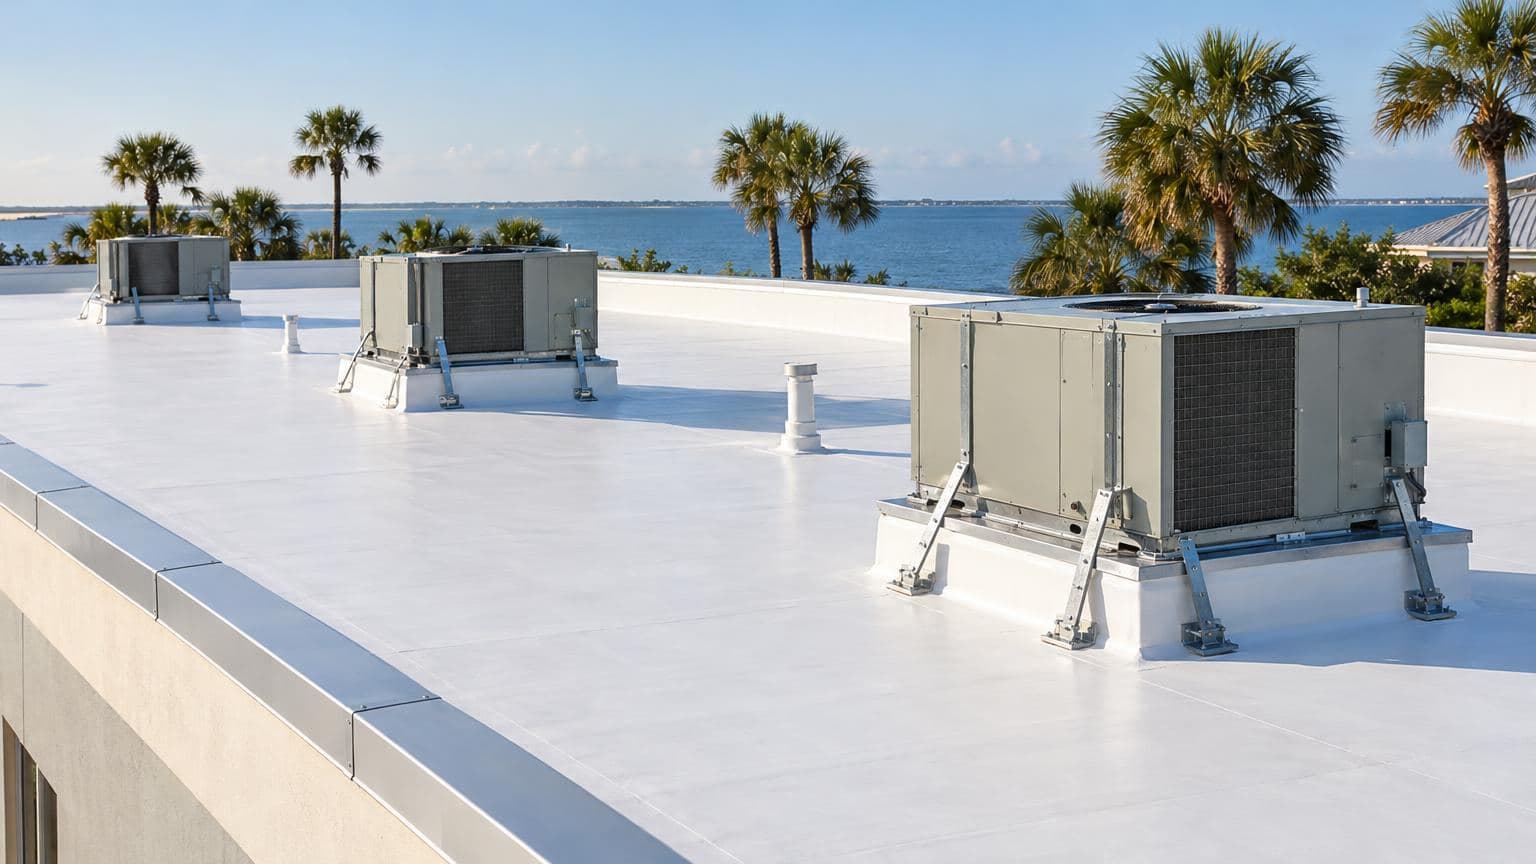
- FORTIFIED Roof: a stronger roofing system, tested gutters and downspouts, a sealed roof deck on steep-slope roofs, impact-tested skylights, and roof-mounted equipment designed for higher wind pressures.1
- FORTIFIED Silver: adds impact-rated walls, impact-rated or protected doors, braced parapets, flood protection for electrical and mechanical equipment, and backup power connections. In hurricane-prone regions, windows must be impact-rated or protected.1
- FORTIFIED Gold: adds an engineered and verified continuous load path, anchored canopies and backup power.1
Some requirements differ between hurricane-prone and high-wind regions. Hail is an optional supplement, and the designation letter states which provisions were met.2
FORTIFIED Commercial covers light to moderate commercial buildings such as hotels, retail stores, schools and mixed-use buildings, and excludes high-hazard occupancies. Apartments and condominiums operated as commercial properties fall under FORTIFIED Multifamily, offered anywhere in the US. Existing buildings with wood-frame roofs must have been built to the 2000 International Building Code or later.3,4,5
An IBHS-certified evaluator reviews drawings and the site, one application per building. The designation stays with the building for 5 years, including after a sale.5
Where you'll see it
- The designation certificate or letter: insurers usually ask to see it before applying a FORTIFIED discount.
- Designation packages: in Alabama, a letter of acceptance, designation documents and a certificate; elsewhere, a letter of compliance listing the mitigation steps.5
- Renewals: where a discount applies, insurers may ask for documentation or recertification at later renewals.
State discount laws and grants
| Alabama | Louisiana | Oklahoma | |
|---|---|---|---|
| Discount law | Ala. Code 27-31D-1 to 27-31D-5 | La. R.S. 22:1483 | 36 O.S. 962 |
| Property covered | Single-family residential or commercial property, modular homes | Residential and commercial property, modular and manufactured homes | Homes retrofitted to FORTIFIED Home High Wind and Hail |
| Insurer duty | Actuarially justified discount on the wind premium | Actuarially justified discount, credit or deductible adjustment on the wind premium | Discount on the wind and hail premium only when the insurer finds it actuarially justified |
| Published amounts | Bulletin 2016-07 benchmarks (example below) | Regulation 136 (homes, hurricane premium, insurers must apply by January 1, 2027): Roof 16% to 29%, Silver 20% to 43%, Gold 24% to 49% | 3% to 42%, by insurer (Oklahoma Insurance Department, March 14, 2024) |
| Roof grant | Up to $10,000, owner-occupied single-family homes in eligible counties | Up to $10,000, primary residences in listed parishes, by lottery | Up to $10,000, owner-occupied single-family homes, with Hail Supplement |
Alabama Act 2015-313 extended required discounts to commercial policyholders. Louisiana's statute names the fortified commercial standard; Regulation 136's published benchmarks are for residential properties.16,12,13
- Alabama and Louisiana: state law requires the designation certificate to be shown to the insurer before the discount takes effect. Louisiana Bulletin 2025-03 (May 21, 2025) makes the certificate the only document needed for the FORTIFIED discount.9,12,17
- Oklahoma: insurers apply the discount at the renewal after the certificate is submitted and may ask for documentation or recertification at later renewals.14
Example: Alabama commercial discount
Alabama Bulletin 2016-07 (October 31, 2016) set benchmark discounts for commercial buildings that are class rated, not for buildings with a specific wind rate from a survey. Insurers may file lower discounts only with detailed actuarial justification. The bulletin's Bronze level is now FORTIFIED Roof, and a May 5, 2025 state report says the bulletin still sets the current discounts.11,18,19
| Zone | Roof (Bronze) | Silver | Gold |
|---|---|---|---|
| Coastal: hurricane premium | 35% | 45% | 50% |
| Central: hurricane premium | 35% | 40% | 45% |
| Northern: hurricane premium | 35% | 35% | 40% |
| All zones: other wind and hail premium | 20% | 25% | 30% |
Take as an example a FORTIFIED Roof building in Mobile County (Coastal Zone) with a $40,000 hurricane premium and a $10,000 other wind and hail premium. The benchmarks give 35% of $40,000 ($14,000) plus 20% of $10,000 ($2,000): $16,000 off $50,000. A non-metal roof older than 5 years loses 10 points from each, giving $10,000 plus $1,000. The discounts are not subject to any total maximum credits rule.11
Questions
- Do insurers have to give a discount for a FORTIFIED roof?
- It depends on the state. Alabama law requires insurers to give residential and commercial policyholders discounts once their buildings meet FORTIFIED standards, and Louisiana law requires an actuarially justified discount for FORTIFIED Home and Commercial. Oklahoma requires one only when the insurer finds it actuarially justified.9,16,12,14
- How long does a FORTIFIED designation last?
- FORTIFIED Commercial and Multifamily designations stay with the building for 5 years from the original designation. FORTIFIED Roof certificates on homes are good for five years, and an evaluator must reinspect the home to renew.4,5,7
- Can an apartment building get FORTIFIED?
- Yes. FORTIFIED Multifamily covers new and existing apartment buildings, condominiums and townhomes operated as commercial properties, with the same Roof, Silver and Gold levels, and IBHS offers it anywhere in the US.4
- Is FORTIFIED the same as building code?
- No. It is a voluntary standard that goes beyond code; the Oklahoma Insurance Department calls it a voluntary beyond-code program.8

Cloudbreak
Cloudbreak keeps every policy, statement of values and loss run in one place per property, tracks renewals, and watches every building against storms with its proprietary predictive storm engine, built with AI and backed by meteorologists.
Sources
Written by the Cloudbreak team. Numbers, dates and rules cite the published sources below.
- 1. IBHS: FORTIFIED Commercial Levels of Resiliency
- 2. IBHS: 2025 FORTIFIED Commercial Standard
- 3. IBHS: FORTIFIED Commercial
- 4. IBHS: Multifamily FAQs
- 5. IBHS: Commercial FAQs
- 6. Alabama Department of Insurance: Strengthen Alabama Homes
- 7. Louisiana Department of Insurance: Fortify Homes
- 8. Oklahoma Insurance Department: OKReady: Strengthen Oklahoma Homes
- 9. Alabama Legislature: Code of Alabama Section 27-31D-2: Premium Discount or Insurance Rate Reduction, Fortified Existing Homes
- 10. Alabama Legislature: Code of Alabama Section 27-31D-3: Insurable Property
- 11. Alabama Department of Insurance: Bulletin No. 2016-07: Premium Discounts and New Commercial and Residential Discounts
- 12. Louisiana State Legislature: La. R.S. 22:1483: Premium Discounts for Compliance with Building Codes and for Damage Mitigation
- 13. Louisiana Department of Insurance: FORTIFIED Benchmarks, Effective January 1, 2027
- 14. Oklahoma State Courts Network (Oklahoma Statutes): 36 O.S. Section 962: Insurance Discount for Homes Retrofitted to Meet High Wind and Hail Standards
- 15. Oklahoma Insurance Department: Strengthen Oklahoma Homes Act: Making Your Home Resilient While Saving You Money
- 16. Alabama Department of Insurance: New Wind Mitigation Discounts
- 17. Louisiana Department of Insurance: Bulletin 2025-03: Discounts and Endorsements for the FORTIFIED Roof
- 18. Alabama Department of Insurance: Bulletin No. 2024-03: Hurricane Sally Data Call
- 19. Alabama Department of Insurance and University of Alabama Center for Risk and Insurance Research: Performance of IBHS FORTIFIED Home Construction in Hurricane Sally