First notice of loss
Claims · Cloudbreak team · Updated October 29, 2026 · 7 sources
Definition
First notice of loss (FNOL) is the first report of a loss or damage to the insurer, and the step that opens a claim. Property policies make prompt notice one of the insured's duties after a loss.
How it works
An FNOL is usually short: the policy, when and where the loss happened, what caused it, what was damaged and how to reach the insured. It can come by phone, online or through an agent. It opens the insurer's claim file and starts any deadlines the insurer has to meet.
The standard ISO commercial property form, CP 00 10, lists the insured's duties after a loss in its Loss Conditions (Section E). They include prompt notice of the loss with a description of the property involved and, as soon as possible, how, when and where it happened. The insured must also take reasonable steps to protect the property from further damage and keep a record of those costs.1
The notice is not the proof of loss. CP 00 10 also asks for a signed, sworn proof of loss within 60 days after the insurer requests it. FEMA's NFIP Claims Manual says a flood claim begins with the written notice of loss and that failure to give timely notice can be a basis for denial; its examples of a harmful delay include reporting the loss after repairs are done.1,2
Notice also starts the insurer's clock. State claim-handling rules set deadlines for acknowledging a claim, investigating it and deciding it, and both the deadlines and what counts as notice vary from state to state.
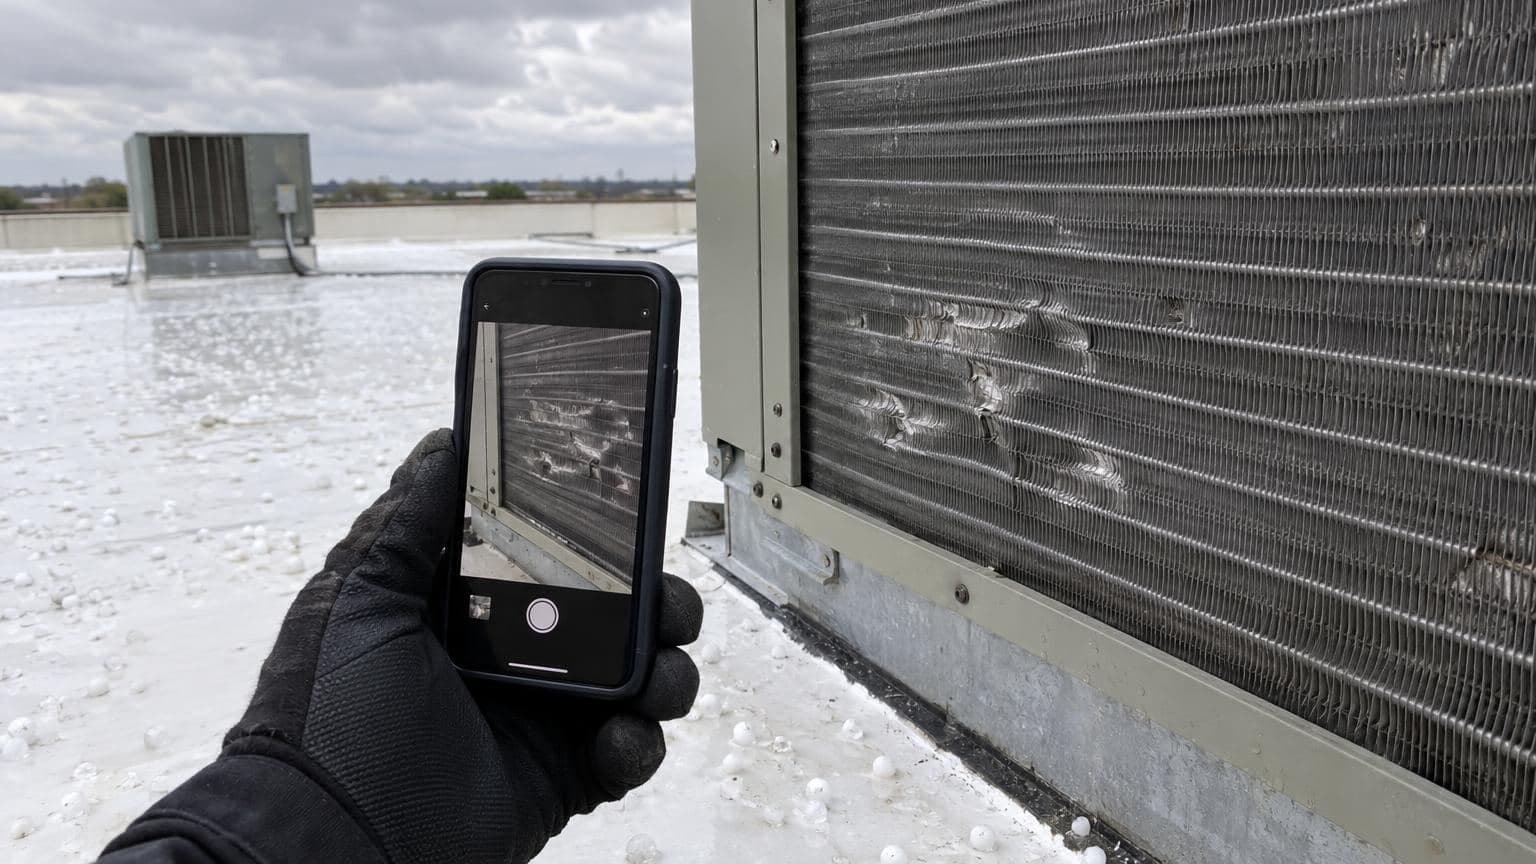
Example: a Texas hail claim
Texas deadlines under Chapter 542 for an example hail claim. The storm and filing dates are examples; the day counts come from the statute. Business days skip weekends and Texas holidays.3
| Step | Rule | Date |
|---|---|---|
| Hail damages the building (example) | Thursday, August 20, 2026 | |
| Insurer receives written notice of claim (example) | Monday, August 24, 2026 | |
| Acknowledge, start investigating, request items | 15th day, Sec. 542.055 | Tuesday, September 8, 2026 |
| Same step after a weather-related catastrophe, as defined by the commissioner | 15 more days, Sec. 542.059 | Wednesday, September 23, 2026 |
| Insurer receives every item it requested (example) | Friday, September 25, 2026 | |
| Accept or reject in writing | 15th business day, Sec. 542.056 | Friday, October 16, 2026 |
| Pay, if accepted on Thursday, October 1 (example) | 5th business day, Sec. 542.057 | Thursday, October 8, 2026 |
An eligible surplus lines insurer has 30 business days, not 15 days, to acknowledge the claim, and 20 business days, not 5, to pay once it accepts.3
The policyholder's own reporting deadline runs the other way. A TWIA policyholder in Texas has one year from the date the property was damaged to report the claim, so this example storm must be reported by August 20, 2027.4
State rules
- Texas: an insurer must acknowledge the claim, start any investigation and request the items it needs within 15 days after it receives notice of a claim, or 30 business days for an eligible surplus lines insurer. The statute defines notice of claim as any written notification that reasonably tells the insurer the facts of the claim.3
- Florida: a residential property insurer must review and acknowledge a claim communication within 7 calendar days and, for a notice of claim, send claim forms, instructions and a phone number. It must pay or deny within 60 days after notice of the claim on residential policies and on commercial property policies for buildings of 10,000 square feet or less.5
- Florida: a claim is barred unless notice is given within 1 year after the date of loss, and a supplemental claim within 18 months. For weather claims, the date of loss is the date the hurricane made landfall or the date NOAA verifies the tornado, windstorm or other weather event.6
Where you'll see it
- The policy: the Duties In The Event Of Loss Or Damage condition in CP 00 10, and Article VII.G.1 of the NFIP Dwelling and General Property flood policies.1,2
- Insurer claim channels. In Texas, for example, TWIA takes claims through its portal, chat, text message and a 24-hour phone line, and asks for the policy number, what caused the damage, a brief description, contact details and any photos.4
- FEMA forms: the NFIP Claims Manual includes a First Notice of Loss form in Appendix C.2
- Lender servicing. When a borrower fails to give notice of a casualty event, Fannie Mae's Form 4636.NMD has the servicer submit a default request within 5 business days of learning of it, with the date of loss, the loss amount, loss runs from the carriers and the proof of loss.7
Questions
- What does FNOL mean in insurance?
- FNOL stands for first notice of loss: the first report of a loss to the insurer, which opens the claim.
- How long do you have to report a property insurance claim?
- It depends on the policy and the state. ISO's CP 00 10 asks for prompt notice and sets no number of days. Florida bars a claim not noticed within 1 year after the date of loss, and in Texas, TWIA allows one year from the date of damage.1,6,4
- Is a first notice of loss the same as a proof of loss?
- No. The notice opens the claim; the proof of loss is the policyholder's signed, sworn statement of the amount claimed. CP 00 10 asks for it within 60 days after the insurer requests it.2,1
- How fast must an insurer respond after first notice of loss?
- State law sets the deadline. In Texas, it is 15 days after notice to acknowledge the claim and start investigating, or 30 business days for an eligible surplus lines insurer.3

Cloudbreak
Cloudbreak keeps a dated record of every roof section, elevation and rooftop unit before a storm, in photos, drone video and notes, with original files and timestamps intact.
Sources
Written by the Cloudbreak team. Numbers, dates and rules cite the published sources below.
- 1. Insurance Services Office (copy hosted by Independent Insurance Agents of Texas): Building and Personal Property Coverage Form, CP 00 10 10 12
- 2. FEMA, National Flood Insurance Program: NFIP Claims Manual (March 2025)
- 3. Texas Legislature: Texas Insurance Code Chapter 542, Processing and Settlement of Claims
- 4. Texas Windstorm Insurance Association: Claims Process
- 5. Florida Legislature: Florida Statutes Section 627.70131, Insurer's duty to acknowledge communications regarding claims; investigation (2025)
- 6. Florida Legislature: Florida Statutes Section 627.70132, Notice of property insurance claim (2025)
- 7. Fannie Mae: Form 4636.NMD, Multifamily Loss Mitigation Non-Monetary Default (September 2025)