Exposure management
Risk · Cloudbreak team · Updated October 29, 2026 · 5 sources
Definition
Exposure management is the set of systems and processes an insurer or reinsurer uses to record, monitor and assess the risks it underwrites, especially catastrophe risk that accumulates when one event can damage many insured properties at once.
How it works
Most property claims are independent of each other, but a hurricane, hailstorm or earthquake damages many insured properties at once. Exposure management watches those accumulations so that no single event, or bad year, costs more than the insurer can absorb.
The risk builds quietly. The American Academy of Actuaries warns that a book left unmonitored through long stretches without a catastrophe can build up growing concentrations of catastrophe exposure. Its 2001 monograph on catastrophe management describes the work in five steps:1
- Set the risk appetite: how much loss in a period the insurer can absorb.
- Measure exposure: take stock of what is on the books, in absolute terms and against that appetite.
- Price for it, more and more often with catastrophe models.
- Control it where exposure exceeds capacity.
- Check the insurer's ability to pay catastrophe losses.
Exposure can be measured simply or with models. In a disaster-prone area, written premium, the number of insured buildings, policy counts or the sum of limits are easy measures. Insurers with significant hurricane or earthquake exposure commonly use catastrophe models to estimate a probable maximum loss (PML) for a given return period.
Example
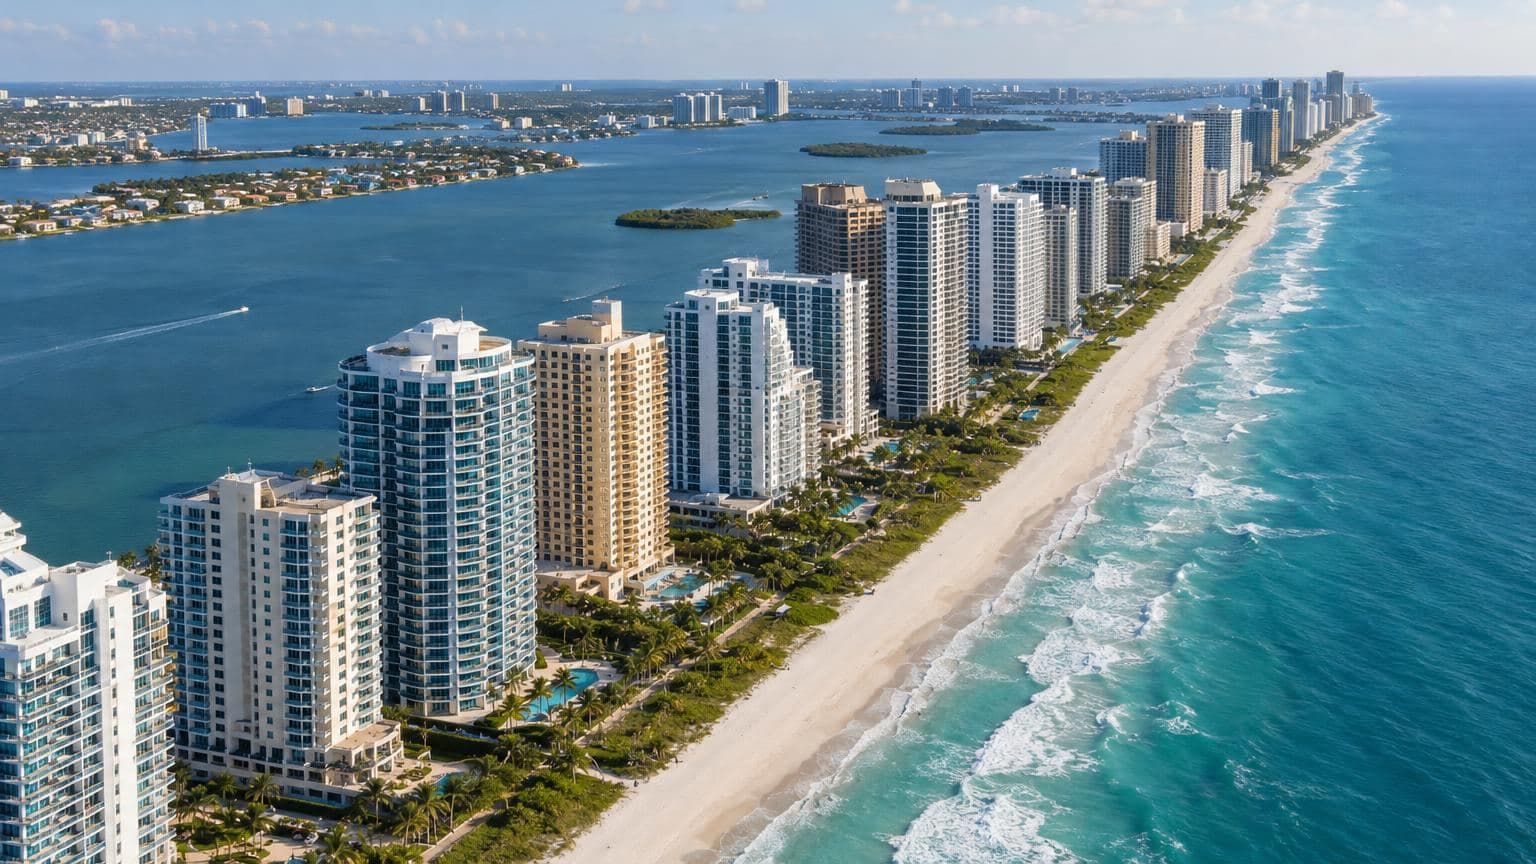
Location drives the result. The Academy gives a simple case: insuring 1,000 homes spread around Florida may not be a problem, while insuring 1,000 homes in coastal Miami-Dade may expose an insurer to an unacceptable level of loss. Two insurers with similar 100-year PMLs can also see very different changes from buying the same portfolio.2
Example inputs: an insurer sets its appetite as a 1-in-100 occurrence loss of no more than $100 million, one of the forms Lloyd's lists, and flags an early warning at 90% of that threshold. Its model shows $92 million, so it is already past the warning line. Adding a block of coastal apartments that raises the 1-in-100 loss by $12 million would take it to $104 million, over the limit.3
Controls
When exposure in an area runs past the appetite, insurers have a few levers:
- Targeted growth elsewhere that offsets an existing accumulation.
- Quotas or a moratorium on new business.
- Minimum deductibles.
- Excluding certain catastrophe perils, or limiting coverage for property prone to catastrophe damage.
- Reinsurance or capital market transfer.
Lloyd's adds that risks a capital model cannot capture may be managed through policy wording or sublimits.3
Lloyd's rules
- Lloyd's Minimum Standard MS6 (January 2020): managing agents needed documented exposure policies, appetite statements, and data entered into a risk recording system when risks were underwritten. Boards were expected to get exposure reports at least every six months, and going over Lloyd's thresholds needed Lloyd's approval.3
- Ways to state appetite: the same standard lists a probabilistic loss (for example, a 1-in-100 occurrence loss no greater than a set amount), a deterministic scenario loss, and aggregate exposure such as county-level totals.3
- Realistic Disaster Scenarios: compulsory scenarios include two consecutive Atlantic seaboard windstorms, a Florida windstorm, a Gulf of Mexico windstorm and a New Madrid earthquake.4
Where you'll see it
- Property data requests at quote and renewal. For a material peril such as US earthquake, Lloyd's says property data may include street-level geocoding and key building characteristics, and NAIC notes model uncertainty rises as a location match drops from parcel to postal code.3,5
- Underwriting terms in catastrophe-prone areas, where the controls above show up as limits on new business, minimum deductibles, excluded perils or sublimits.
Questions
- What is an accumulation in insurance?
- A group of insured exposures that one event can damage at the same time. Lloyd's says catastrophe risk covers any class where major, accumulating, non-independent events could occur, not only natural catastrophes on property.1,3
- Is exposure management the same as catastrophe modeling?
- No. Modeling is one way to estimate losses. Exposure management also covers recording data, setting appetite, monitoring exposures against limits, controls and reporting to management.
- What are Lloyd's Realistic Disaster Scenarios?
- Set disaster events that Lloyd's uses to stress test each syndicate and the market as a whole. Every syndicate reports its estimated losses for the compulsory scenarios.4
- How often do insurers review exposures?
- It varies by insurer. Lloyd's January 2020 exposure standard expects board reporting at least every six months and says annual reporting is unlikely to be enough.3

Cloudbreak
Cloudbreak keeps every policy, statement of values and loss run in one place per property, tracks renewals, and watches every building against storms with its proprietary predictive storm engine, built with AI and backed by meteorologists.
Sources
Written by the Cloudbreak team. Numbers, dates and rules cite the published sources below.
- 1. American Academy of Actuaries, Catastrophe Management Work Group: Insurance Industry Catastrophe Management Practices (June 2001)
- 2. American Academy of Actuaries, Extreme Events and Property Lines Committee: Uses of Catastrophe Model Output (July 2018)
- 3. Lloyd's: Lloyd's Minimum Standards MS6: Exposure Management (January 2020)
- 4. Lloyd's: Realistic Disaster Scenarios
- 5. National Association of Insurance Commissioners (NAIC): NAIC Catastrophe Modeling Primer (adopted August 13, 2025), Attachment Three to Executive (EX) Committee and Plenary minutes